Choosing the Courage of Conviction Over the Comfort of Consensus
In 1846, Danish philosopher Soren Kierkegaard wrote, “The crowd is untruth” — a concept worthy of a sticky note on the refrigerator of time. Nearly two centuries later, the full quote, “There is a view of life which holds that where the crowd is, there also is the truth…but this is a lie. The crowd is untruth,” seems to accurately capture state of today’s social interaction, political environment, and capital markets.
Is Confidence Better Borrowed or Earned?
Kierkegaard’s point wasn’t that group think is always wrong, rather that individuals often surrender responsibility to collective judgment. Shared beliefs require little effort to hold, and they offer the illusion of comfort because the weight of responsibility is distributed across a crowd. Conviction, on the other hand, demands true grit, requiring a healthy mix of deep thinking, tolerance for discomfort, intellectual honesty, and willingness to disagree with pundits. At its best, conviction supplants the borrowed comfort of “safety in numbers” with an earned confidence that values evidence over popularity.
This may not seem like a significant revelation, until one considers that many breakthroughs in science, medicine, and business emerged first as a conviction opposed by consensus. Nicolaus Copernicus spent decades asserting, against the fierce resistance of the Church and the scientific establishment of his time, that the Earth was not flat, a conviction that found its proof in 1522 when Ferdinand Magellan’s crew became the first to circumnavigate the globe. Galileo’s challenge to the accepted “fact” that the Sun revolved around the Earth sparked the Scientific Revolution in 1610, reshaping humanity’s understanding of the cosmos. More recently, Dr. Barry Marshall won a Nobel Prize in 2005 after deliberately consuming the bacteria he believed caused ulcers, ultimately proving to an entrenched medical establishment that stress and diet were not to blame.
Similarly, the commercial marketplace has given us myriad market-defining products that were initially panned. The Walkman was dismissed as a novelty, the iPhone as an overpriced toy, and Post-it Notes, alluded to earlier, barely made it out of product development. In each case, informed conviction outlasted the skepticism of the crowd, not because it changed minds, but because the evidence ultimately confirmed what had been true all along.
The Message for Investors
Financial markets have their own history of consensus becoming disconnected from reality. The dot com bubble, the Great Financial Crisis, recurring meme-stock surges, and today’s AI exuberance all followed a similar pattern: capital chasing popularity rather than fundamentals until the gap between price and value became too wide to ignore.
The tension between conviction and consensus is on full display across today’s capital markets, where consensus-based, algorithmic investing seems to disproportionately drive market movements. A significant share of capital flows into a handful of widely followed companies and narrative-driven theses, where positive expectations for future performance are already baked into current pricing. The result is a growing sameness in security selection and decision-making that runs directly counter to the goal of outperforming the market.
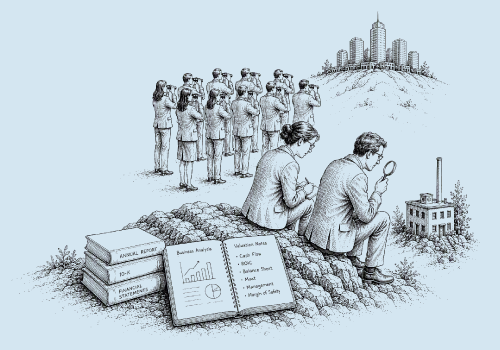
By contrast, the conviction-based practice of value investing directs capital toward misunderstood securities and underfollowed companies, opportunities where deep research can uncover significant value yet unrecognized by market participants. Put simply, consensus offers borrowed comfort; conviction offers earned confidence, anchored in independent analysis rather than inherited belief. Or, as the father of value investing, Benjamin Graham, famously put it, “You are neither right nor wrong because the crowd disagrees with you. You are right because your data and reasoning are right.”
Value Investing is Not a Casual Endeavor
At its core, value investing is about finding businesses trading at a discount to their intrinsic value due to temporary market misjudgment, with a clear catalyst expected to close the gap between current price and estimated value. While the merits and principles of value investing are straightforward, the practice is intensive and demanding. Developing conviction in an investment thesis requires rigorous analysis, and the work doesn’t end once an investment is made. That conviction must be tested continuously, both before committing capital and throughout the lifecycle of the investment. This isn’t about being contrarian for its own sake: without evidence, conviction is simply speculation. Supported by disciplined analysis, conviction becomes the foundation of value investing.
That foundation requires an ongoing commitment, sustained across market cycles: studying businesses, evaluating management teams, monitoring new developments, assessing industry dynamics, and searching for insights that other investors and analysts may overlook. Markets move quickly, information is abundant and ever changing, and separating what matters from what doesn’t is a skill that few market participants possess or have the temperament to master. When an investor hires a firm built around this discipline, they are selecting a team with a specific mindset and the purpose-built capacity and expertise to execute this strategy day in and day out.
Attuned for What's Ahead
The core tenets of value investing established by Benjamin Graham decades ago prove time-tested. However, the environment in which they are applied has changed. Today’s investors have near-instant access to information, sophisticated analytical platforms, artificial intelligence tools, and real-time market data. While these developments unquestionably improve efficiency, they also create a subtle risk: confusing access to, or possession of, information with the ability to understand what that information means or how it should be correctly interpreted. Few market participants are equipped with the specialized expertise needed to tell the difference.
In today’s investment world, many firms trade the art of due diligence for something increasingly commoditized and digitized: analysts review financial statements, earnings transcripts, industry reports, and market data without ever leaving their desks. These tools, while indispensable, provide convenience at a cost: overreliance and a tendency to overlook what the data don’t show.
Businesses are ultimately run by people, influenced by culture, driven by incentives, and shaped by operational subtleties that no spreadsheet or algorithm can capture. So how do investors account for the aspects of due diligence that can’t be commoditized or simply reduced to a number?
At Global Value Investment Corporation (GVIC), we answer that question by putting boots on the ground, a foundational element of our approach that has remained in place since our founding in 2007. We visit management offices, field operations, and customer-facing facilities, meeting directly with the people who run the business, observing how they operate, and learning how they manage. We assess the operational subtleties that live outside the numbers — supply chain efficiency, technology use, and the quality of the customer experience, to name a few. That first hand research doesn’t replace forensic financial analysis; it completes it.
Equally important, where investors look for intrinsic value has evolved. Traditionally, value investors focused largely on identifying discounts to historical measures of worth, including assets, earnings, or cash flow. While these measures remain important, value also comes from sources that quantitative measures so often fail to reflect: intellectual property, brand strength, proprietary technology, and the je ne sais quoi of leadership with the acumen to execute on a sound strategy. Identifying these opportunities requires an investment lens that looks for both a gap between price and value and a catalyst capable of closing it. This same lens also helps identify and avoid “value traps”— securities that appear undervalued today primarily because they are deteriorating in value with no real catalyst to close the gap or prevent a continued decline.
Identifying a catalyst is only part of the equation; realizing it requires active engagement. Rather than viewing ownership as a passive exercise, GVIC works constructively and directly with management teams to encourage accountability, strengthen performance, and help unlock value over time. Conviction, in this sense, is not merely an investment thesis; it is an ongoing commitment to serve as a catalyst in the realization of that thesis. At GVIC, when we commit capital to an investment, our work has just begun.
Consensus may offer comfort. Conviction demands effort. As access to information grows and due diligence becomes increasingly commoditized, that so-called comfort only becomes easier to find – and earned confidence harder to come by. We believe GVIC’s commitment to thorough research, opportunistic investment, and active engagement positions us to navigate market complexities with conviction, capturing unrealized value in overlooked opportunities, and building enduring financial foundations for the firm’s clients, across decades, not quarters. That conviction drives our team to uncover differentiated opportunities in an increasingly consensus-based investment marketplace.